Your 2026 Medicare bill came from your 2024 tax return. Social Security's surcharge runs $1,148 to $6,936 a year, per person. If one of 8 events fits you, you can get it lowered.
Medicare.gov; Social Security AdministrationLower your Medicare bill with our Premium Rewind Method™.
This guide gives you everything you need to ask Social Security for a lower premium: the form, how to fill it in, and the proof that gets it approved. Your income fell. The bill did not. Our Premium Rewind Method™ walks you through it, one step at a time.
- Know tonight which of the 8 events fits you
- File on an estimate instead of waiting 2 years
- Keep it from happening again next year

One-time payment. Instant access.
30-day money-back guarantee.
The letter never mentions the form
Every Medicare bill is set from a 2 year old tax return. If your income was higher then, a letter comes from Social Security, not from Medicare. Yours may have come already, or it is on its way. It is correct by the rule and wrong about your life now.
The letter says the amount went up. It does not say why, or what to do. You did not earn more this year. So you pay it.
Nothing on it says you can ask them to look again. No line, no number.
The form is free. What costs you is not knowing which of the 8 events fits, or what to send.
We wrote this because the letter will not. Which of the 8 events fits you, what to send, and by when. Our Premium Rewind Method™, start to finish.
What people say when the letter comes
Real experiences from people in exactly your situation.
One truck, double the bill
"Retired at 67. As planned, withdrew a large sum to pay cash for a truck. It was just enough to push our combined income over the Medicare “threshold”. It doubled “both” of our monthly Medicare fees. We had no clue this would happen. [...]"
A retiree, in a public comment
Found out too late
"[...] When you retire (most of us) won't be making our full pay like we were when we were WORKING. So I'm supposed to sell my house for what I paid for it so [the surcharge] doesn't drown me in a medicare premium I can't afford?!!!!!???? [...] Didn't hear about this [surcharge] stuff till this week. I was looking forward to downsizing and selling off all the stuff my life collected through the years."
A homeowner, in a public comment
Triple the Part B
"My [surcharge] more than triples my Part B payment [...] learning about it was a bit of a shock."
A retiree, in a public comment
$109 to $504, each
"We me[t] IRMAA in 2019 after the sale of inherited property we sold in 2017. Monthly medicare premium went from $109 to $504 per month EACH! I turned 65 in 2019. Wish somebody would have informed us about this in advance."
A couple, in a public comment
Inherited money, higher bill
"[...] I inherited $250,000, my Medicare for 2025 is going to be $480, it would have been $185."
A retiree, in a public comment
Downsize, pay more
"Especially difficult when you sell a home to downsize and you find out your Medicare premiums go extremely high"
A retiree, in a public comment
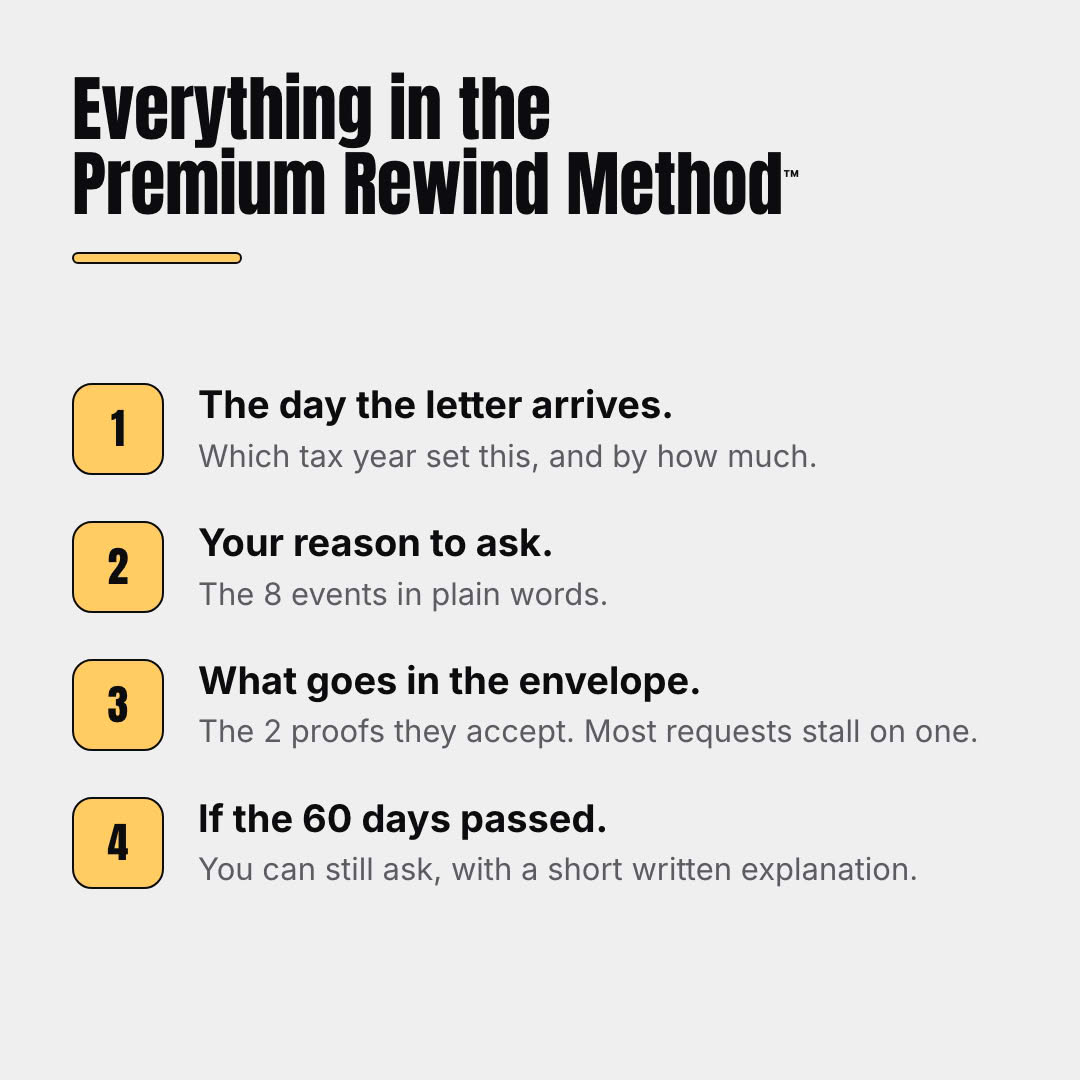
Everything in the Premium Rewind Method™
Step by step, from the letter to a lower bill.
- The whole Premium Rewind Method™, start to finish. How one free form can lower a premium set by a tax return from 2 years ago.
- The day the letter arrives. Which year's tax return set this, and how far past the line you landed.
- Finding your reason to ask. The 8 events in plain words, including the one almost everybody misreads.
- File now, not next year. How to use an estimate of this year's income, and the 1 thing to check before you send it.
- What goes in the envelope. The 2 proofs they accept. Most requests stall because only 1 was sent.
- Filling in the form. Step by step, including the step most people should leave blank. You will send it knowing nothing is missing.
- If the 60 days already passed. You can still ask, with a short written explanation. The guide shows you what to write.
- Never again pay a premium set by a year that is over. You will know each year whether yours still fits your income.
- A printable one-pager to work from. Keep it with the letter so you always know what to do next.
None of the 8 fits you? You can still pay less next year
Some readers check the list and find nothing that matches. That is not the end of the story. Your bill is set fresh every year, from a tax return 2 years back, so one high year falls off on its own. The second part of our Premium Rewind Method™ shows you how to plan ahead, so a high year never sets your bill again.
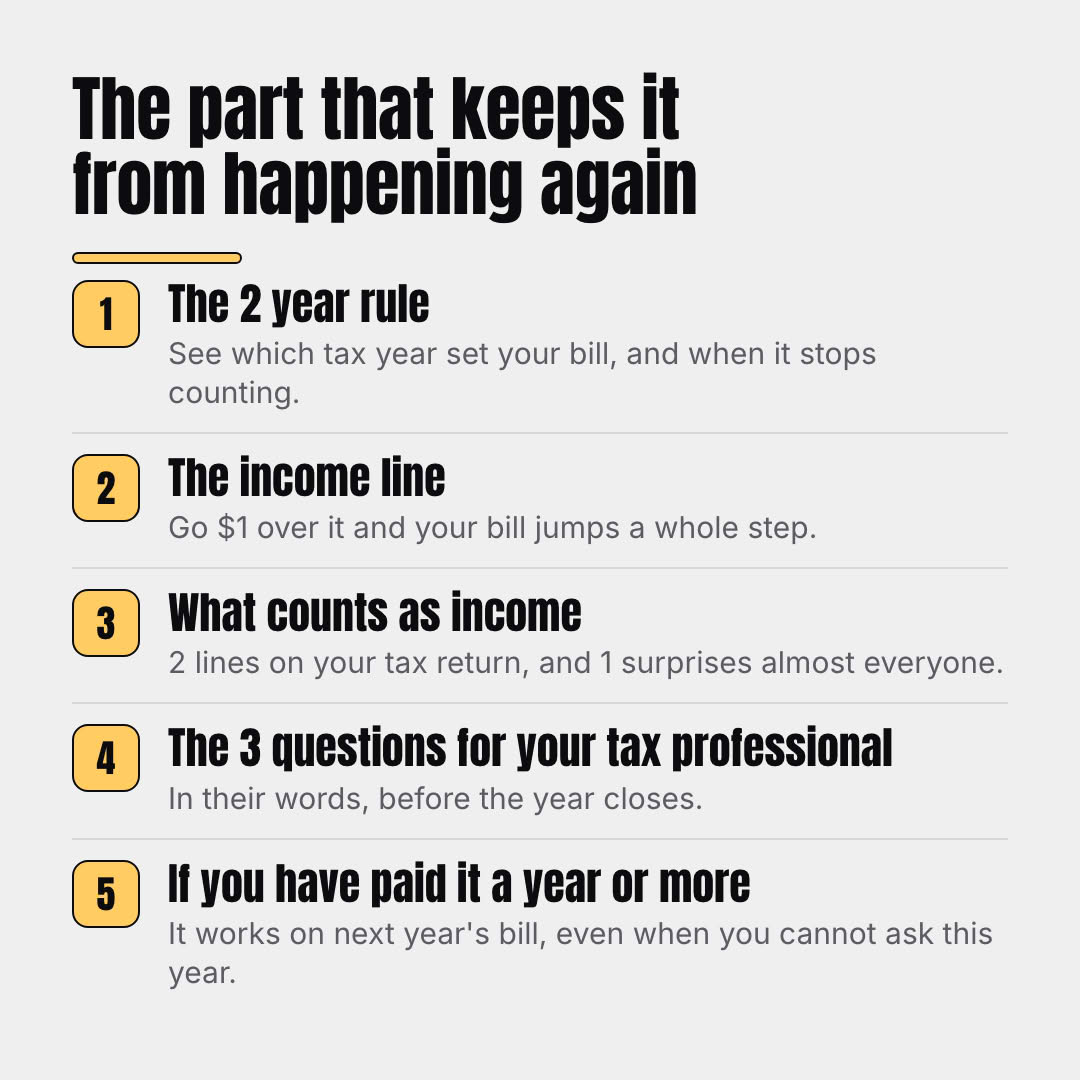
The part that keeps it from happening again
Our Premium Rewind Method™ does not stop when you send the form. The other part is making sure it does not happen again, and nobody warns you before the year closes.
- The 2 year rule. See which tax year set your bill, and when it stops counting.
- The income line. Go $1 over it and your bill jumps a whole step. The guide shows you where the line is.
- What counts as income. It is 2 lines on your tax return, and 1 of them surprises almost everyone.
- The 3 questions to ask your tax professional, in their words.
- What to do if you have already been paying the extra charge for a year or more.
This is the part that works on next year's bill, even when you cannot ask this year.
Where do you even look?
"It'd be helpful to know how much money you can make this year [...] that's what people really need to know! so what I made in 2023 will affect my premium in 2025. How do I know how much that is? Nobody tells anybody or where do you go to find it"
A reader, in a public comment
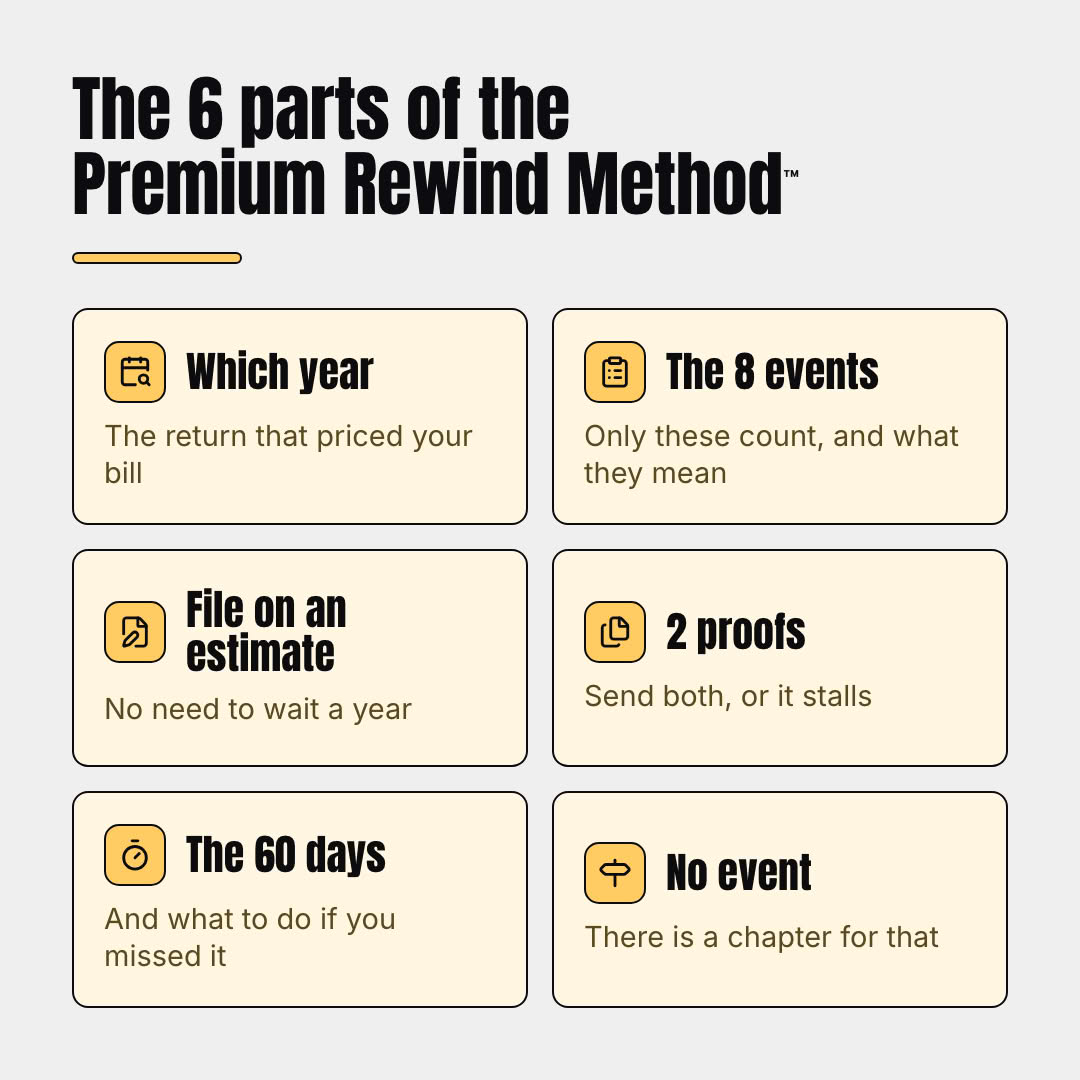
The 6 parts of the Premium Rewind Method™
Together they are the method that gives you the best chance at a lower premium.
Which year
The return that priced your bill
The 8 events
Only these count, and what they mean
File on an estimate
No need to wait a year
2 proofs
Send both, or it stalls
The 60 days
And what to do if you missed it
No event
There is a chapter for that
You will know which year set it, which event applies, what to send, and by when.
This is for you if any one of these fits
- A letter arrived and the amount was higher than you expected
- No letter yet, but you want to be ready the day one comes
- You have never checked whether your premium matches your income now
- You stopped working, cut back, or had one unusual year of income
- You would rather follow clear steps tonight
- You want that money back in your pocket every month
The best investment you will make this year
When to start, what it costs, and why it pays for itself.
You are not too early or too late
If the letter has already come, there is a route for you, even if it has been sitting for months. If it has not come yet, this is the calm time to get ready. Either way, the first step takes 10 minutes.
This guide pays for itself
It costs less than one dinner out. The surcharge Social Security adds runs into the thousands a year, for each person it applies to. The guide is one payment, and it keeps working every year.
Read it risk free
If the guide is not useful to you, email info@savethisguide.com within 30 days and we will refund you in full. No questions asked.
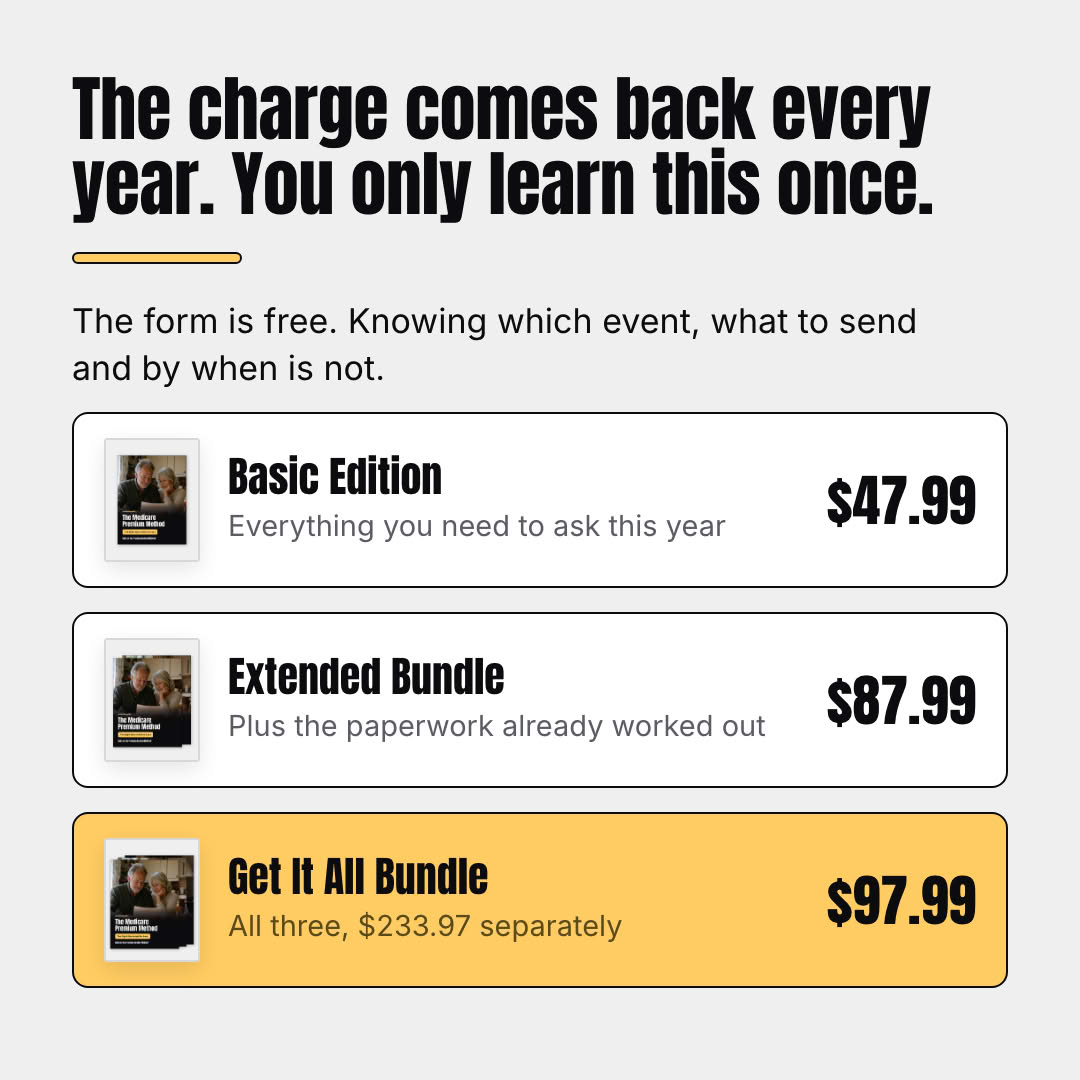
The charge comes back every year. You only learn this once.
The form is free. Knowing which event, what to send and by when is not. One payment, no subscription. The more you get, the more situations and years it covers.
Basic Edition
Everything you need to ask this year. Find the year that set your premium. Check your life against the 8 events. Then file on an estimate, using the walkthrough of the form. Covers your own case. And if none of the 8 events fits you, the chapter on what to do instead. Want the paperwork worked out for you? For $40 more, see the Extended Bundle.
Extended Bundle
Everything above, plus the paperwork already worked out. The do-not-file check, which stops a wasted filing before you start. The sheet that picks which tax year goes in the box, the one people get wrong. What to attach for your event, listed out. The version for couples. And the questions to ask your tax professional, which work even in a year when no event fits. Want the upcoming years covered too? For $10 more, see the Get It All Bundle.
Get It All Bundle
Everything above, plus every year after this one. The Second Ask: what to do when the first answer is no. What to do if you have already been paying it. And Every New Edition: any new version of this product we release in the future is yours at no extra cost. Best for anyone who wants to learn this once and stay current.
Next year's bill is being set right now, from a tax return that is 2 years old. Whichever bundle you pick, it is risk free: full refund within 30 days.
One-time payment. Instant access.
30-day money-back guarantee.
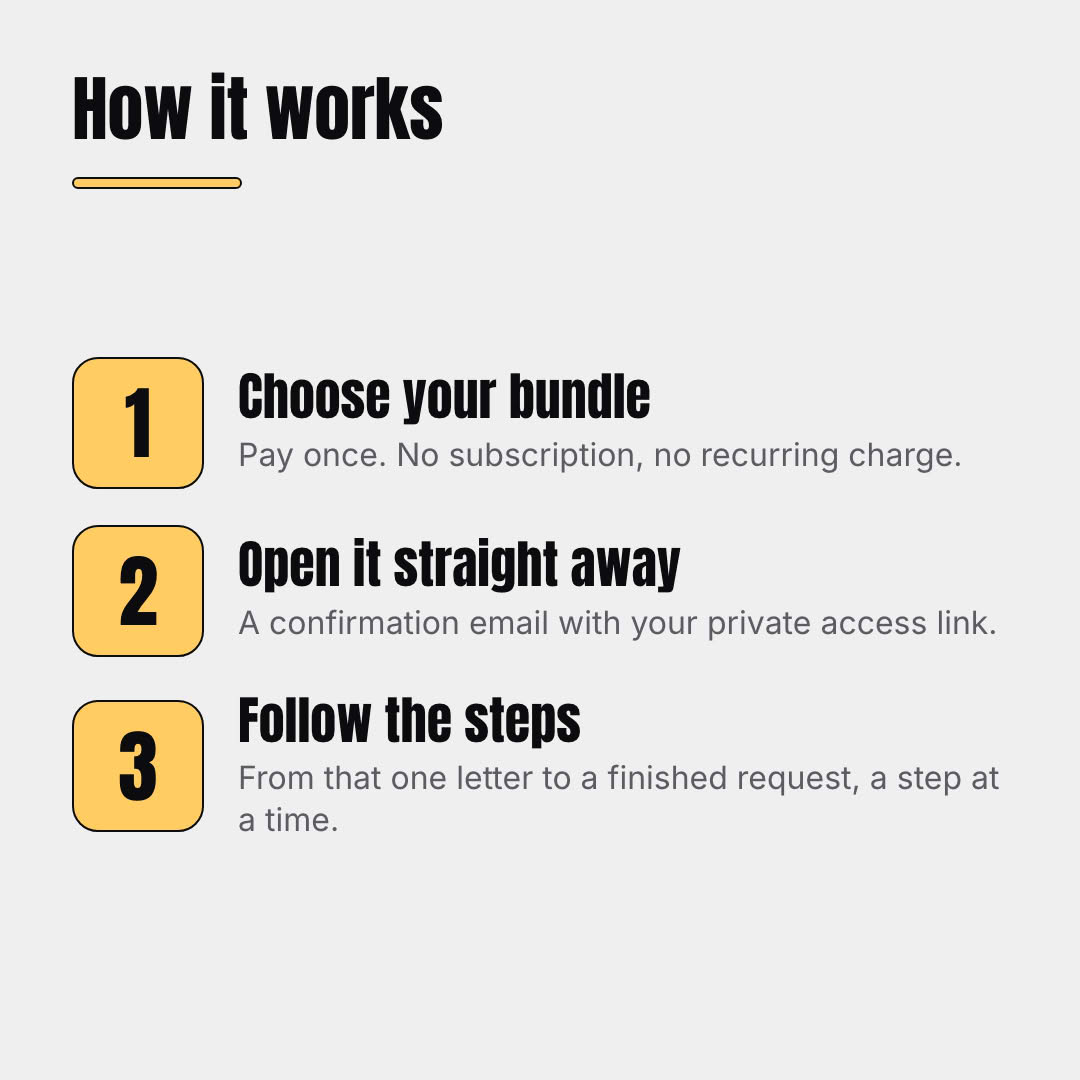
How it works
3 steps, and you will know exactly what to do.
Choose your bundle
Pay once. No subscription, no recurring charge.
Open it straight away
You get a confirmation email with your private access link to your PDF files. Read them on your phone, your computer, or print them.
Follow the steps
Whether your letter has come or not, the guide takes you to a finished request, one step at a time.
Frequently Asked Questions
Does this work if I am not sure I qualify?
Yes. The guide walks you through the 8 events so you can tell quickly, and it has a full chapter for readers who match none of them. That chapter is about the upcoming years, not the form.
Can I use this if my letter is already old?
Yes. There is a chapter on late requests, which are still accepted when you send a short written explanation. The part about the upcoming years does not depend on the 60 days at all.
Is this a subscription?
No. It is a one time payment for the bundle you choose. No recurring charges and no hidden fees.
How long do I have access?
Forever. The guide is a PDF you download and keep. Your access link stays in your confirmation email.
Will my premium definitely go down?
That depends on whether one of the 8 events fits you, and the first step in the guide is finding out. If one does, it shows you exactly what to send and by when. If none does, there is an entire chapter for the upcoming years.
Do I need an accountant or an advisor?
No. The form is designed to be filed by the person it applies to, and Social Security accepts it directly from you online, by fax, by post, or in person. The guide does include the questions to put to a tax professional if you already use one, and everything is laid out in order, so you can even hand it to them and they will know exactly what you are asking for.
Is this a physical book?
It is a digital guide in PDF form. It downloads right after you pay. It is also designed to print easily at home if you prefer paper.
What if I already hired a company?
You can still use it. The guide has a section on deciding between doing it yourself, a flat fee service, and leaving it with someone you already pay. It shows you what to check in any agreement before you pay for another year.
How do I get a refund?
Email info@savethisguide.com within 30 days of your purchase date and we will refund you in full.
Do you update the guide?
Yes. The income lines reset every year, so we do reissue the guide. We do not promise a schedule. Everyone with the Get It All Bundle gets every new version we release, at no extra cost.
Find out how to lower your Medicare bill today.
Download our Premium Rewind Method™ and take the first step in 10 minutes. If one of the 8 events fits you, it walks you through getting it lowered. Next year's bill is coming either way. You can be ready for it, or be surprised by it.
Get the guide for $47.99 →One-time payment. Love it or full refund.If one of 8 life events fits you, you can get it lowered. That rule is Medicare.gov and Social Security's, not ours.